Is Buying a Car with a Promissory Note Safe? Risks and Things to Watch Out For
Share This Page
Buying a car with promissory notes is a legal and common financing method; however, its safety depends not on the car itself but on the party conducting the transaction and the nature of the signed contract. A promissory note is a valuable instrument in which the buyer commits to paying a specific amount on a specific date; when it goes unpaid, it is a shortcut to enforcement proceedings, liens, and the sale of the vehicle to cover the debt. This method only becomes a reasonable alternative if the conditions are clearly set out in writing.
Highlights
- Selling a vehicle with promissory notes is a legal method; it must be arranged in compliance with the Turkish Commercial Code and the Code of Obligations.
- The down payment rate varies from practice to practice: between 20% and 50% , with terms mostly limited to 36-48 months .
- If the notes go unpaid, enforcement proceedings begin; a vehicle under lien can be sold through enforcement to cover the receivable.
- After 3 years have passed from the due date of the note, its enforceability as a valuable instrument becomes an issue.
- Even if the debt is settled, the vehicle cannot be sold before the lien annotation is removed at the notary.
How Does Buying a Vehicle with Promissory Notes Work?
The logic of the system is simple: the full or partial price of the vehicle is delivered in exchange for promissory notes divided into specific payment dates. The dealer transfers the vehicle and, in return, receives notes with set due dates and amounts. Since the note is, in legal terms, a valuable instrument documenting the buyer's payment commitment, the seller gains a concrete enforcement tool at the first delay.
In practice, the most common scenario is structured as follows: the buyer pays the down payment, takes delivery of the vehicle, a lien or mortgage is established in favor of the seller, and this lien is removed once the notes are paid off. In transactions without a lien or contract, the registration certificate may remain with the seller; since this is an arrangement where the actual ownership of the vehicle remains ambiguous, it is necessary to approach it with caution from the start. In a notarized sale, the official contract states that the price has been paid; the parties separately establish their term and lien arrangements with an additional contract.
Commercial terms vary significantly from seller to seller. Some companies go down to 20% down payment and 36 months , while some extend up to 48 months. Common conditions include having SGK or Bag-Kur registration, having no enforcement record, mandatory comprehensive insurance and contracted inspection requirements, and in some cases a guarantor being requested. Model age can also determine the down payment: increasing the down payment rate for older models is a common practice. Speaking as someone who has been through the wringer in this business: as the list of conditions grows, the buyer's position narrows, but at least the boundaries of that narrowing position become visible.
What Happens If the Note Goes Unpaid?
The answer to this question summarizes the entire risk profile of the method. For an unpaid promissory note, a protest is first issued; then the seller proceeds to enforcement proceedings and seizure actions are initiated against the debtor. The debtor's assets, including the vehicle, can be sold through enforcement to cover the debt. This picture becomes even more concrete with a vehicle under lien: when the notes fall into default, the vehicle is sold in enforcement, and the seller's receivable is covered from the sale proceeds. The remaining issue does not end there; expenses such as attorney fees and file charges are also borne by the buyer.
The seller being able to apply additional interest to the payment plan is a separate matter. A one or two-month delay in the monthly installment can push the total debt far beyond what you expected. Moreover, the note is not a simple debt document; as a valuable instrument, it can change hands and be endorsed. Issues of enforcement as a valuable instrument come into play after 3 years have passed from the due date on the note; meaning that in a long-term plan, the legal status of the final notes is also a matter that needs separate consideration.
There is also the matter of aval. A person who signs the aval endorsement on the note falls into the position of a joint and several debtor; no courtesy such as first pursuing the debtor is granted for collecting the receivable. Experienced users calling a signature under an aval "worse than being a guarantor" is not for nothing. Even as a guarantor you have certain defenses available, but with an aval, the debt is hung around your neck along with the note.
Vehicle Seizure and Lien Status: A Mandatory Check Before Purchase
With a note-based purchase, there are two separate seizure-lien questions. The first is whether the vehicle you are buying already has a seizure or lien on it; the second is whether the note-based purchase itself creates a lien on the vehicle. For the first, the task is easy: you can check the seizure on the vehicle through the vehicle seizure inquiry service offered on e-Devlet. The detail to be aware of is that the presence of a seizure on the vehicle does not legally prevent its sale; however, to protect the creditors, the vehicle must be registered as seized. In practice, there are also those who argue that the annotation must be cleared for the sale to be completed at the notary; so there may be a difference between theory and the counter. The rule is this: a seized or liened vehicle can be bought, but the buyer is deemed to have accepted that seizure and lien as well.
The second question, namely the lien created by note-based purchase, is a mandatory safeguard by the nature of the method. When is this lien removed? When the debt is fully paid, when the notes are returned, and when the lien annotation is officially removed at the notary. You cannot sell the vehicle without the annotation being removed; even if the payments are complete, the transaction is not officially finalized. For the removal of the lien and seizure, a letter obtained from the enforcement office along with the vehicle owner's ID photocopy or power of attorney is required. A buyer who does not address this paperwork after the sale is completed will be stuck when they want to transfer the car later.
Promissory Note or Auto Loan?
The best-selling argument for buying with a promissory note is that you don't pay bank interest. For buyers with problems in their bank records who cannot get approval for a vehicle loan, this method offers a real way out; the target audience of these transactions is already largely those who cannot get credit. However, the phrase "no interest" is often misleading. In a sale with a promissory note, instead of interest, the cost is loaded through a price difference reflected in the vehicle, and the total amount can come out close to, or even above, a bank loan. In the past, the promissory note was a flexible arrangement between a local dealership and an acquaintance; now it has become the standard product of institutionalizing companies, and the cost of a standard product has become standardized too.
Concrete comparison examples: in a forum account, 200,000 TL on a 12-month plan, a bank loan totaled approximately 280,000 TL, while buying with a promissory note came to about 300,000 TL ; meaning the difference was almost negligible. On the other hand, it can also be seen that in sample calculations by some companies selling with promissory notes, the promissory method is shown to be as much as 116,800 TL more advantageous. The fact that the two figures diverge so much shows one single thing: the total cost depends entirely on the seller and the payment plan established. In other words, there is no single answer to the question of promissory note or loan; the answer lies within the calculation presented to you.
| Feature | Buying with a Promissory Note | Vehicle Loan |
|---|---|---|
| Cost logic | Through price difference instead of interest | Through bank interest |
| Who can use it | Everyone, including those with credit score problems | Requires bank approval |
| When payment is not missed | Enforcement, seizure, sale of the vehicle | Bank monitoring and possibility of restructuring |
| Security on the vehicle | Lien/mortgage in favor of the seller | Mortgage in favor of the bank |
| Total cost | Varies by seller | Predictable based on interest rate |
Let me add a note to the table: with a bank loan too, the vehicle is mortgaged until the debt is paid off; what distinguishes buying with a promissory note is not the existence of a lien, but the predictability of the cost and the softness of the processes that come into play in case of payment difficulty.
Things to Check Before Signing When Buying a Vehicle with a Promissory Note
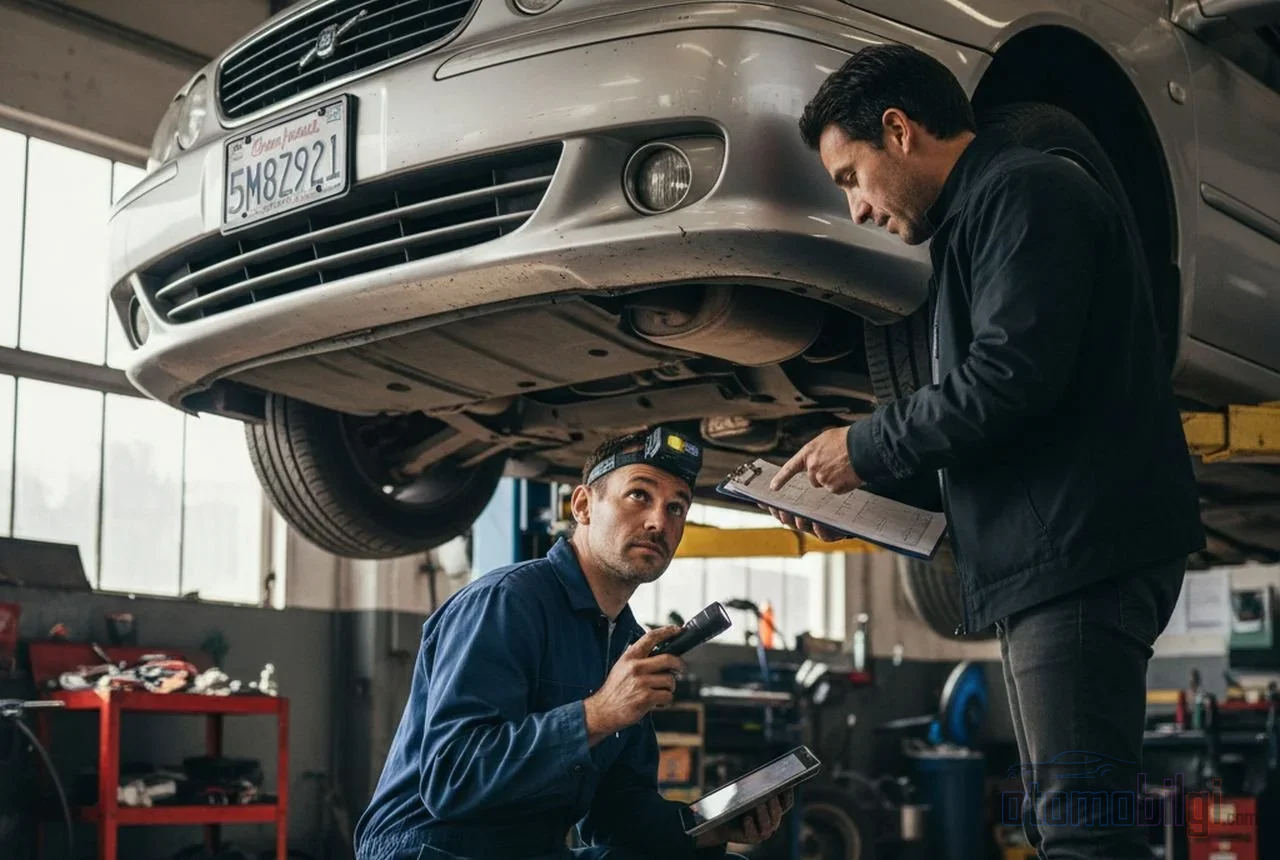
This section is the part of the page that carries the real value. Nothing can be corrected after the signature is made; a promissory note is a valuable document, and it is difficult to later object to the wording on it.
- Research the seller's reliability: references, online reviews, complaint records.
- Make sure the promissory notes are notarized; handwriting, an acquaintance's assurance, or a verbal commitment are not sufficient.
- Bind all conditions in a written contract: interest or price difference, payment plan, late penalty, procedure for removing the lien.
- Have the vehicle's condition checked by a TSE-approved contracted inspection service; do not sign without checking the insurance claim record, mileage consistency, and damage history.
- Ask for the registration, valid traffic insurance, and a statement from e-Devlet showing there is no motor vehicle tax debt.
- Query any seizure on the vehicle through e-Devlet.
- Honestly assess your budget: what matters is not buying the vehicle, but being able to sustain the payments.
Buying from a dealership also involves the issue of contract language. Showing the seller merely in the position of "the vehicle party" in the contract can weaken your consumer rights; the door for what you can sell under the Consumer Law may narrow. Clarify from the start whether the seller is the owner of the vehicle or an agent. To give a practical gauge for common terms: the down payment is generally in the 20-30% range, with terms between 36-48 months; some companies offer an option to defer the first 3 months of payment, while others require payments to be made to designated bank accounts. Each of these items should be clearly written in the contract; verbal confirmation is no substitute for documentation.
Points to Watch When Buying Through a Notary Deed
In a sale made at the notary, the official contract includes a record that the payment was made. In a promissory note purchase, this record may not reflect reality; part of the payment has not yet been made. Having the parties explicitly regulate this situation with an additional contract prevents future disputes for both buyer and seller. A special regulation has also been published regarding the registration and tax obligations of vehicle sales made with a notary deed; it is worthwhile to clarify details such as to whom the tax liability passes before the transaction.
When Can Buying With a Promissory Note Make Sense?
I will not make a rote "never" or "always" recommendation. Buying with a promissory note can be a defensible option if these three conditions are all present: a bank loan is genuinely unavailable, the seller is corporate and the contract is transparent, and the total cost shows a reasonable difference compared to a bank loan. If any one of these three is missing, you have no strong reason to put pen to paper. A term exceeding your payment capacity, a high guarantee (aval) obligation, or a contract in which the lien removal procedure remains unclear will win you not the car, but a seller who has handed you the problem.
Final word: this method is not illegal, but it is unforgiving. A promissory note is, by its nature, a document that tolerates no delay. Test your payment plan not against one bad month but two bad years; if possible, even if you have applied for a loan and been rejected, put the interest rates on the comparison table. A signature on paper weighs as much as the key to the car; do not mix up the order of the two.
Sources
- Is Promissory Note Car Sale Safe?
- Is Buying a Car with a Promissory Note Safe? Things to Consider
- Buying a Vehicle with a Promissory Note: Is It Reliable, What Are the Risks?
- Things to Consider When Buying a Vehicle with a Promissory Note
- Promissory Note or Loan? Vehicle Financing Comparison
- Car Sale with a Promissory Note
- Electronic Lien Inquiry for Vehicles
- A Vehicle Can Be Sold Even If There Is a Lien on It
- What Is Vehicle Lien & Encumbrance Removal? How Is It Done?
- Traffic Registration Procedures - Removal of Liens, Encumbrances and Precautions
- General Communiqué Serial No. 30 on the Registration and Tax Obligation of Vehicle Sales Made with a Notarized Promissory Note (MTV)
- How Is a Vehicle Sale Done at the Notary?
- Collection of Unpaid Promissory Notes
- How Is the Collection of Unpaid Promissory Notes Done?
- What Happens If the Promissory Note Is Not Paid?
- Things to Know About Promissory Notes, According to an Expert
- Things to Consider When Buying a Car with a Promissory Note
- Things to Consider When Buying a Car from a Dealership: 2026 Guide
- What Should You Pay Attention to When Buying a Car from a Dealership?
- Promissory Note Car Purchase Complaints and Reviews