The First 30 Minutes After an Accident: How to File a Report, Take Photos, and Report Damage
Share This Page
The first 30 minutes after an accident means securing life safety first, then properly preserving evidence and filing the damage claim on time: if there are injuries, 112 is called, in material-damage and amicable accidents an accident report is drawn up, vehicles are photographed without being moved, and the damage notification is generally made within 5 business days. A mistake made in these three stages can lead to loss of rights that no paperwork can later compensate. In over thirty years of automotive journalism, I have seen hundreds of accident files; most of the bad outcomes were not faulty vehicles or unfair fault determinations, but procedures that were rushed and left incomplete in the first minutes.
Highlights
- In accidents involving injuries, the first number is always 112; in material-damage and amicable accidents, it is possible to write up a report without calling the police.
- An amicable report is valid only if there is only material damage and the parties agree on how the accident occurred.
- The damage notification must generally be made within 5 business days of the occurrence of the risk; otherwise, loss of rights may arise.
- As of September 1, 2026 traffic and comprehensive insurance damage claims are received through the Alo 193 Joint Damage Notification Center.
- The legal validity period of the accident report is 2 years from the date the accident is learned of.
What should be done in the first minutes after a traffic accident?
The order matters. First, check the health of yourself and your passengers. If there are injuries or worse, the decision-making stage is already over: 112 is called, law enforcement is awaited, and the vehicles must not be touched. If there are no injuries, the procedure turns to a material-damage accident, and here speed and care must go hand in hand.
Turn on the hazard lights and place the warning triangle. There is no fixed 150-meter rule circulating on social media for the warning triangle distance; the common recommendation on urban roads is around 30-50 meters. The real principle is that the triangle should be placed not immediately behind the vehicle, but at a distance where approaching drivers will see it early depending on the speed limit and traffic flow. Also consider the possibility of fire or fuel leakage; if such a risk exists, getting away from the vehicle takes precedence over everything else.
Article 81 of the Highway Traffic Law clearly sets out the driver's obligations: to stop, take traffic safety measures, and present identity, address, driver's license, registration, and insurance information when requested. In the past, accident scenes were debated for years; now, thanks to cameras on phones, fault assessment has largely been left to the photos. This convenience also makes the discipline of taking photos in the first minutes mandatory.
Can an accident report be drawn up in every accident?
No, and this distinction determines the entire process. Under the practice in effect since 2008, a mutually agreed accident report can be drawn up without calling the police or gendarmerie only if there is material damage only and the parties agree on how the accident occurred. If one of the parties avoids signing, if there is a drunk or unlicensed driver, if the driver is a minor, if one of the vehicles has official plates, if there is no mandatory traffic insurance, if public property is damaged, or of course if there are injuries or deaths, the report is drawn up by law enforcement. A report drawn up by the drivers themselves is invalid in these cases.
The situation is different in single-vehicle accidents
In a single-vehicle accident where you hit a barrier, pole, or wall, there is no such thing as the driver drawing up a report with themselves. An official record is mandatory, and repairs are covered only by comprehensive insurance; traffic insurance has nothing to pay you in this scenario. Therefore, in a single-vehicle incident, first securing the scene and then calling the police or gendarmerie comes before calling the insurance company.
Where is the report drawn up and how many copies?
You do not need to wait at the accident scene for the report. After photos are taken, the vehicles can be moved to a suitable place that does not obstruct traffic. On the paper report, the date and time, accident location, witness information, the identity and driver's license details of both drivers, the vehicles' brand, model, plate, chassis, and policy information, and the manner in which the accident occurred along with a sketch are filled in. At least two copies are prepared; an unsigned report or one with a single copy is considered invalid. Sample forms can be obtained from the websites of official institutions; a digitally signed report drawn up with the SBM Mobile Accident Report application is also legally valid and is automatically transmitted to insurance companies. It is also possible to query electronically approved material damage accident reports through e-Devlet.
The report must be drawn up immediately after the accident. A report left until the next day may not be accepted by some insurance companies and may lead to requests for additional evidence. Although the legal deadlines for a compensation lawsuit are generous - 2 years from the date the accident was learned of and 10 years from the date of the accident - in practice, things go smoothly only when started much earlier.
Collecting evidence with photos and video
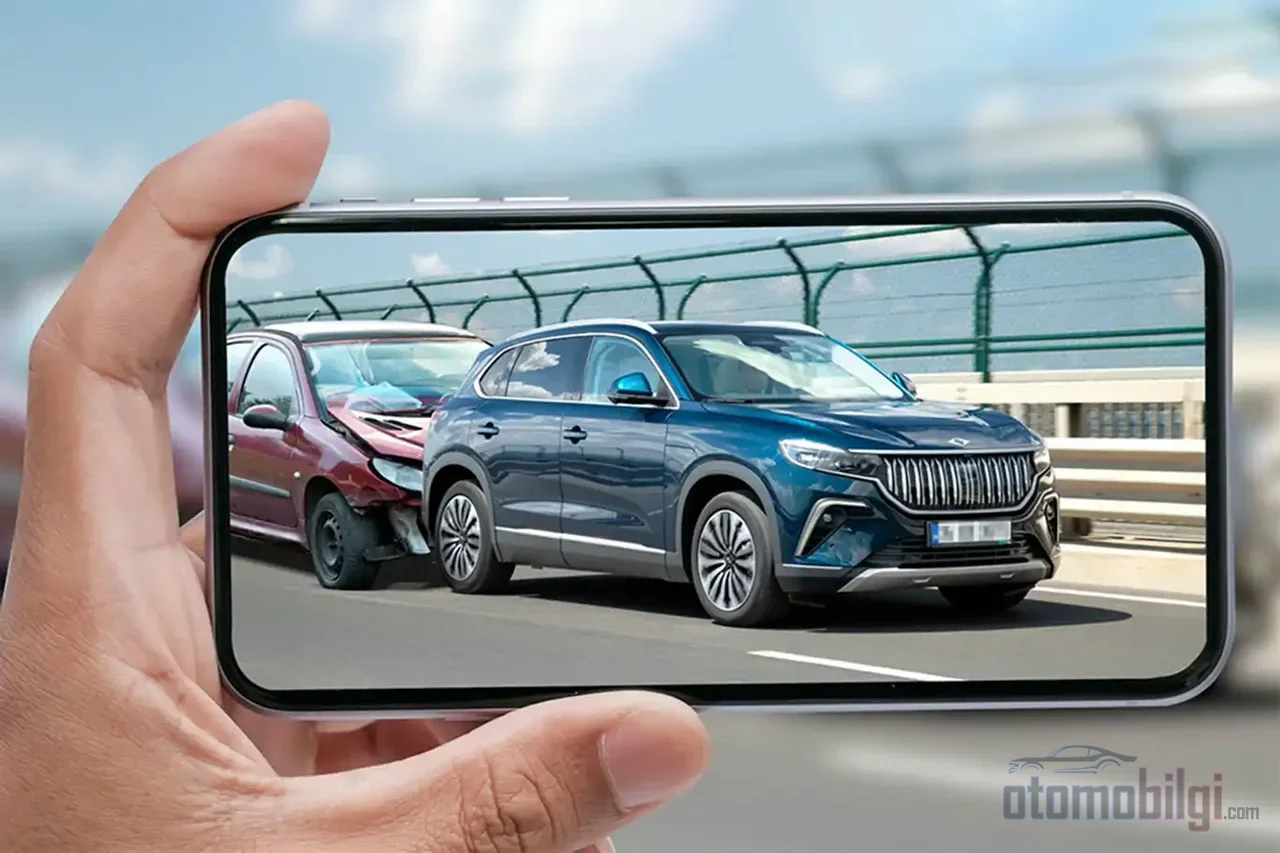
Before the vehicles are moved, the accident scene, the vehicles' positions relative to each other, and the damage must be photographed from different angles. These records are the primary evidence in fault assessment; no matter how carefully the sketch in the report is drawn, it does not replace photographs. The main things to capture are:
- The plates and general position of both vehicles
- Close-ups of damage details
- Brake and tire marks, broken glass
- Road condition, signs, intersection layout
- The other party's identity, driver's license, registration, and traffic insurance policy information
- Contact information of witnesses, if any
In-car camera footage serves as strong evidence, especially in accidents involving disputes. Files from drivers who use dashcams are resolved with a clarity that would have been hard to imagine a decade ago; this is one of the rare areas where technology genuinely proves its worth.
How and within what timeframe should a damage claim be filed?
In traffic and comprehensive insurance, the damage notification period is 5 days from the occurrence of the risk; in policy general terms, this period is mostly set at 5 business days. Written accident reports and photos must be submitted to the insurance company within at most 5 business days from the date you learned of the accident; with a mobile report, this submission is automatic. If notification is not made on time, you may lose your rights. As of September 1, 2026, damage claims for motor vehicle insurance are received through the Alo 193 Joint Damage Notification Center; the alo193.gov.tr web portal and mobile app are also among the official channels. Of course, the companies' own call centers and mobile apps also continue to operate.
Clarifying in advance who will receive what is useful in terms of expectation management:
| Scenario | Paying coverage |
|---|---|
| The other party is 100% at fault | The other party's traffic insurance |
| You are at fault, the other vehicle is damaged | Your traffic insurance pays for the other party's damage |
| You are at fault, your own vehicle is damaged | Comprehensive coverage only |
| Single-vehicle accident (barrier, pole, wall) | Comprehensive coverage only, with an official report required |
Comprehensive insurance damage payments are made within 10 business days after the documents are completed and the damage is assessed; in any case, payment must be made within at most 45 days from notification. In accidents with material damage, payment in practice usually occurs within about 8 business days. If the damage amount exceeds one-tenth of the insurance coverage - 40,000 TL for 2026 - an appraiser is automatically appointed and the appraiser information is sent via SMS; since the damage amount and loss of value are calculated in the same appraiser report, in most cases you do not need to file a separate claim for loss of value. Payments have also changed: previously payment could be made to intermediaries, now the damage amount is sent directly to the rightful owner's IBAN.
Can a fault determination be appealed?
Yes, it can. If insurance companies cannot agree on the fault ratio, the file goes to the Accident Fault Assessment Committee; the result is usually announced within 3 business days. The policyholder can appeal the fault ratio via sbm.org.tr or e-Devlet, and the right to appeal the results is limited by a deadline; late appeals are considered invalid. Therefore, do not just leave the document containing the fault ratio on the table as it arrives; if you believe it is wrong, quickly file an appeal with supporting documents. Let us add one final warning: companies compare the accident time with the policy issuance time minute by minute. A policy purchased after the accident has no retroactive effect, and attempting to later charge a claim to the policy counts as insurance fraud. Those who try this end up not just with a denied file, but with a criminal record.
Frequently asked questions
Is a police report always required in an accident with material damage?
No. If there are no injuries, the parties agree on how the accident occurred, and none of the exceptional cases listed above apply, an agreed accident report is sufficient.
What should be done if the other party refuses to sign?
Call the police or gendarmerie via 112 and have an official report drawn up. If the other party has no traffic insurance at all, the police are called again and a report is recorded; the victim has the right to file a lawsuit.
Can a no-report accident process be initiated?
In an accident involving only material damage, an insurance claim process without a report cannot be initiated. In an accident involving injury or death, the absence of a report means an administrative fine and criminal liability come into play.
The first 30 minutes are the 30 minutes that determine everything else. Ensure safety, secure the evidence, fill out the paperwork completely, and make the notification within the deadline; the rest is already what the procedure will take care of.
Sources
- What Should Be Done Immediately After a Traffic Accident? A Step-by-Step Damage Guide
- Accident Report (official form)
- Material Damage Traffic Accident Report Inquiry
- Alo 193 Insurance Damage Notification Hotline
- Comprehensive Insurance Damage Repair Process
- Is There a Deadline for Damage Notification?
- Post-Accident Response Areas