What Does Traffic Insurance Pay For, and What Doesn't It Cover?
Share This Page
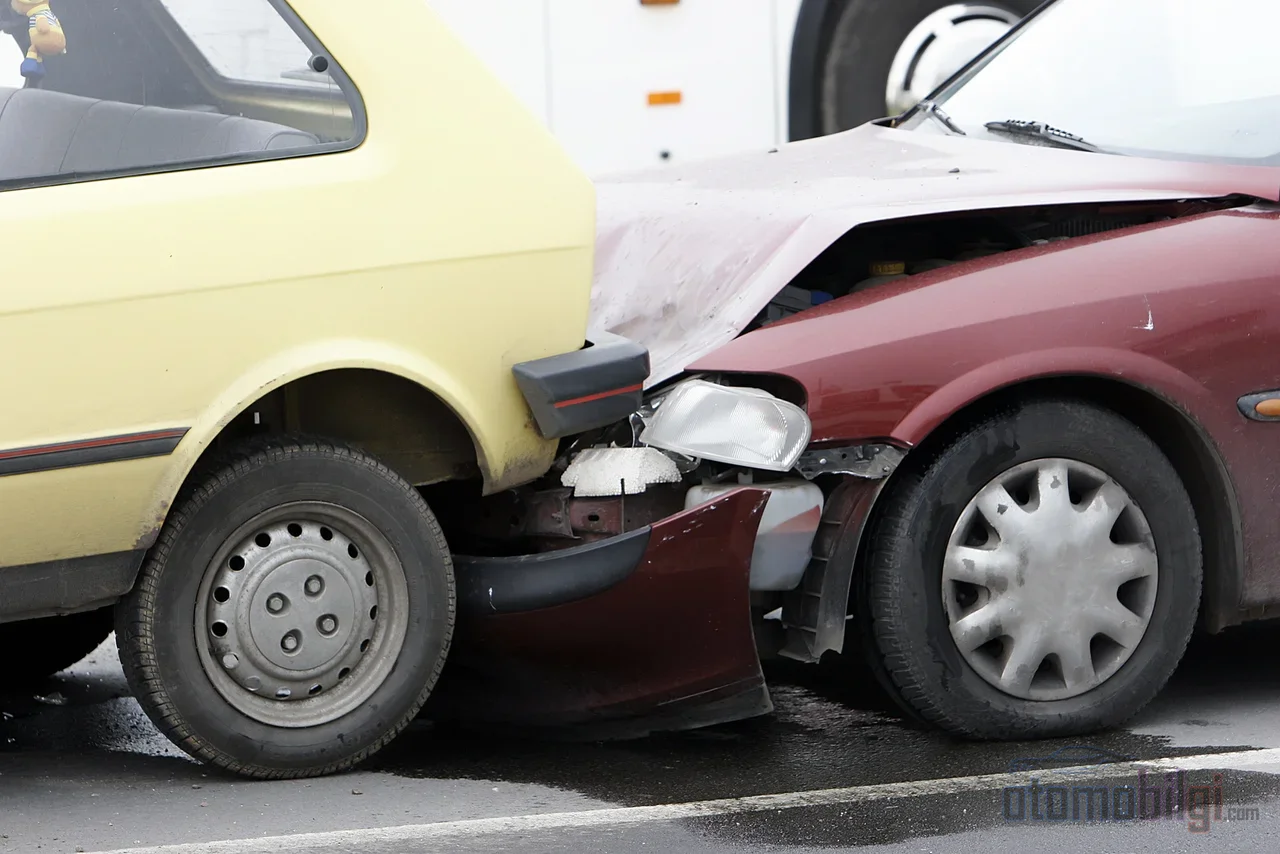
Mandatory traffic insurance covers the other party's bodily and material damages within certain limits if you are at fault in an accident; damage to the at-fault driver's own vehicle is excluded and only comprehensive coverage (kasko) takes care of it. This is the fundamental rule that millions of drivers who renew their policy every year still have not fully internalized, and learning it after an accident comes at a very high price.
Highlights
- In 2026, the material damage coverage per vehicle is 400,000 TL, per accident 800,000 TL, an increase.
- The bodily injury limit is per person 3,600,000 TL; the per-accident cap varies by vehicle group.
- Damage to the at-fault driver's own vehicle is not covered by traffic insurance.
- In cases of drunk driving or driving without a license, the insurer may pay and then seek recourse from the driver.
- Compensation claims for moral damages are excluded from the scope of mandatory traffic insurance.
What Does Mandatory Traffic Insurance Cover, and Up to What Limit?
The policy's official name is the Highway Motor Vehicles Mandatory Financial Liability Insurance; Article 91 of the Highway Traffic Law No. 2918 obliges every vehicle operator to obtain this insurance. Article 85 of the law captures the essence in a single sentence: the insurer is liable for the faults of the operator, the driver, and their assistants as if they were its own. In other words, if the accident is your fault, your policy is the door the other party will knock on to seek their rights.
The definition of "the other party" here should be kept broad. Traffic insurance covers not only the other vehicle; it also covers pedestrians, passengers in the other vehicle, immovable properties belonging to third parties such as houses, shops, and gardens, as well as public property such as utility poles, barriers, and signs. The material coverage determined per accident is distributed proportionally among the injured parties. For example, if in an accident the other party's vehicle and the window of a shop are damaged, the per-accident material limit is shared between these two damages.
Limits show the maximum amount that will be covered for a single incident. If the limit is exceeded, the difference is claimed from the at-fault driver. The only potential savior at this point is the Voluntary Financial Liability (VFL) coverage added to the comprehensive policy; the standard traffic policy does not include this additional coverage. If there is no VFL either, the amount exceeding the limit is paid out of the driver's own pocket. This is the first sentence someone who has been in this business for thirty years would say: the limit figure looks high, but in a serious accident, when bodily injuries are involved, the numbers run out faster than you expect.
What Are the 2026 Coverage Limits?
The 2026 period limits set by the SEDDK have been in effect since January 1, 2026, with the rationale being the compensation of rights holders' damages in line with current economic conditions. For material damage, the per-vehicle limit rose from 300,000 TL to 400,000 TL, and the per-accident limit rose from 600,000 TL to 800,000 TL; for bodily injury, the per-person amount increased from 2.7 million to 3.6 million TL. The increase applies to all policies in force without any additional premium. Compared with the 2026 period, the table is as follows:
| Vehicle Group | Material Damage (Per Vehicle / Per Accident) | Bodily Injury (Per Person) | Bodily Injury (Per Accident) |
|---|---|---|---|
| Passenger transport (automobiles etc.) | 400,000 TL / 800,000 TL | 3,600,000 TL | 18,000,000 TL |
| Goods transport, trailers, work machines | 400,000 TL / 800,000 TL | 3,600,000 TL | 36,000,000 TL |
| Agricultural and special-purpose vehicles | 400,000 TL / 800,000 TL | 3,600,000 TL | 18,000,000 TL |
| Motorcycles and cargo motorcycles | 400,000 TL / 800,000 TL | 3,600,000 TL | 10,800,000 TL |
These figures need to be read in everyday language. In an accident where you are 100% at fault, the other party's vehicle damage, up to the portion covered by the limit, concerns your policy, not their traffic insurance; in partially at-fault accidents, everyone covers the other party's damage in proportion to their own fault. If the parties are 40%-60% at fault, payments are divided according to these ratios. Let us also add that in today's picture, where spare part prices are running high, the material damage limit fills up quickly in major collisions; a bumper replacement used to be accounted for, now the same money barely covers a headlight assembly.
Does Traffic Insurance Cover My Own Vehicle? How Does It Differ from Comprehensive Insurance?
No, it does not; let that be the clearest sentence on this page. In an accident where you are at fault, damage to your own vehicle is entirely outside the scope of mandatory traffic insurance. Traffic insurance protects the other party; comprehensive insurance protects your own vehicle. One is a legal requirement, the other an optional product; they are not alternatives to each other but complements. This is exactly where the confusion arises, because dealers and guide sites explain both on the same page.
| Feature | Traffic Insurance | Comprehensive Insurance |
|---|---|---|
| Whose damage it covers | The other party's (third parties') | The insured's own vehicle |
| Legal status | Mandatory | Optional |
| Damage to your own vehicle | Not covered | Covered depending on the policy |
| Theft, fire, natural disasters | Out of scope | May be covered depending on the guarantees |
In an accident involving a driver with comprehensive insurance, both parties' damages can be partially or fully covered: the other party's damage from your traffic policy, and the damage to your own vehicle from your comprehensive insurance. For a driver without comprehensive insurance, an at-fault accident means the repair cost of the vehicle comes directly out of their own pocket. The rule is similar on the depreciation side: the depreciation of the faultless or less-at-fault party is claimed from the at-fault party's traffic insurance; if the other party has no insurance or insufficient coverage, their own comprehensive insurance comes into play.
Situations Where Traffic Insurance Does Not Pay
Knowing what the policy does not pay is as important as knowing what it does; because the reason for rejection is often learned after the accident. Common exclusions are as follows:
- Damages caused while the vehicle was not in motion
- Indirect damages such as work stoppage, loss of income
- Damages to the at-fault policyholder's own vehicle
- Damages to goods carried on a trailer (except items belonging to the other party)
- Moral compensation claims and lawsuits; these claims can only come to the agenda with a court decision
- Material damages resulting from a stolen vehicle being involved in an accident
- Damages arising from the transport of explosive materials
- The accident-involved vehicles belonging to the same person
- Accidents occurring where the vehicle was put up for sale or sent for maintenance
It would be appropriate to add a few more headings to this list. Driving under the influence of alcohol or drugs, intentional accidents and fraud attempts, driving with an expired policy, and driving without a license or with a license not matching the vehicle class are among the headings that disable the insurer's coverage. Your own medical expenses, as well as the vehicle being stolen, burned, or damaged by natural disasters, are also not covered by this policy; those are matters for comprehensive (kasko) insurance. The fact that towing fees are not covered is also a detail that often surprises the unfortunate driver.
Right of Recourse: The Insurer Pays, Then Can Recover It From You
Recourse is the right of someone who pays another person's debt to reclaim the amount paid from the party actually responsible. In insurance, this is called the principle of subrogation: after the insurer pays compensation to the injured party, it steps into that party's rights against the person liable for the damage. In other words, the company does not neglect the victim, but it looks at who truly deserves to bear the cost.
The fundamental condition for the insurer to have recourse against the operator is that the accident resulted from the intentional act or gross fault of the operator and the persons for whom the operator is responsible. In practice, the most common cases are drunk driving, driving without a license, and gross fault. In such cases, the insurer first pays the victim; the precondition is that the compensation has been paid to the insured in full. It then reclaims the amount paid from the operator. On the other hand, it is not possible to hold the operator liable for compensation paid to the victim for a driver who is not drunk or unlicensed; recourse does not arise in every accident, but depending on the severity of the fault.
A similar form of protection operates through the Guarantee Fund (Güvence Hesabı) in uninsured vehicle accidents. The Fund pays for bodily injuries, disability, and loss of support compensation caused by vehicles without a policy; however, its liability is limited to the limits of a valid policy, and it does not cover accidents involving insured vehicles. After payment, recourse is made against the responsible party - meaning the Fund is not an insurance equivalent, but a fund of last resort.
Frequently Asked Questions
If the other party is at fault, whose insurance pays for my damage?
It is covered from the other party's traffic insurance up to your fault percentage. If the other party is 100% at fault, your entire damage is covered by their policy; in cases of partial fault, payment is divided according to the fault ratios. By law, no insurance company - whether or not you are at fault - may add the other party's damage to your damage amount; it is recorded in the TRAMER registry in this manner.
Are loss of value and moral compensation paid?
Loss of value can be claimed from the other party's traffic insurance if they are at fault. Moral compensation, however, falls outside the scope of mandatory traffic insurance; this claim can only be raised through the courts, and the general statute of limitations is two years.
Are natural disaster and theft damages covered by traffic insurance?
No. Risks such as floods, hail, fire, and theft fall within the coverage of comprehensive insurance policies. The sole task of mandatory traffic insurance is to ensure that the damage caused to the other party in an accident is covered within certain limits; nothing that happens to your own vehicle is within the scope of this policy.
The Bottom Line
Mandatory traffic insurance is the other party's insurance in an accident, not yours. Sitting at the accident desk without knowing the coverage limits, how fault ratios affect payments, and the situations where payment is denied or recourse is sought is the most expensive way to learn the lesson. If you want both your vehicle and yourself to stay protected, this policy meets the minimum amount required by law; the rest is up to your comprehensive insurance and your own caution.
Sources
- Coverage Limits - Mandatory Traffic Insurance Limits
- KMAZMSS Coverage Limits
- Coverage Limits
- What Does Traffic Insurance Cover, and What Are the 2026 Limits?
- What Is the 2026 Traffic Insurance Coverage Limit?
- Traffic Insurance Damage Compensation Conditions
- What Does Mandatory Traffic Insurance Not Cover?
- Differences Between Traffic Insurance and Comprehensive Insurance
- Vehicle Diminished Value
- Comprehensive/Traffic Insurance Subrogation Lawsuit