Why Doesn't Comprehensive Insurance Cover Every Kind of Damage? Exclusions in the Policy
Share This Page
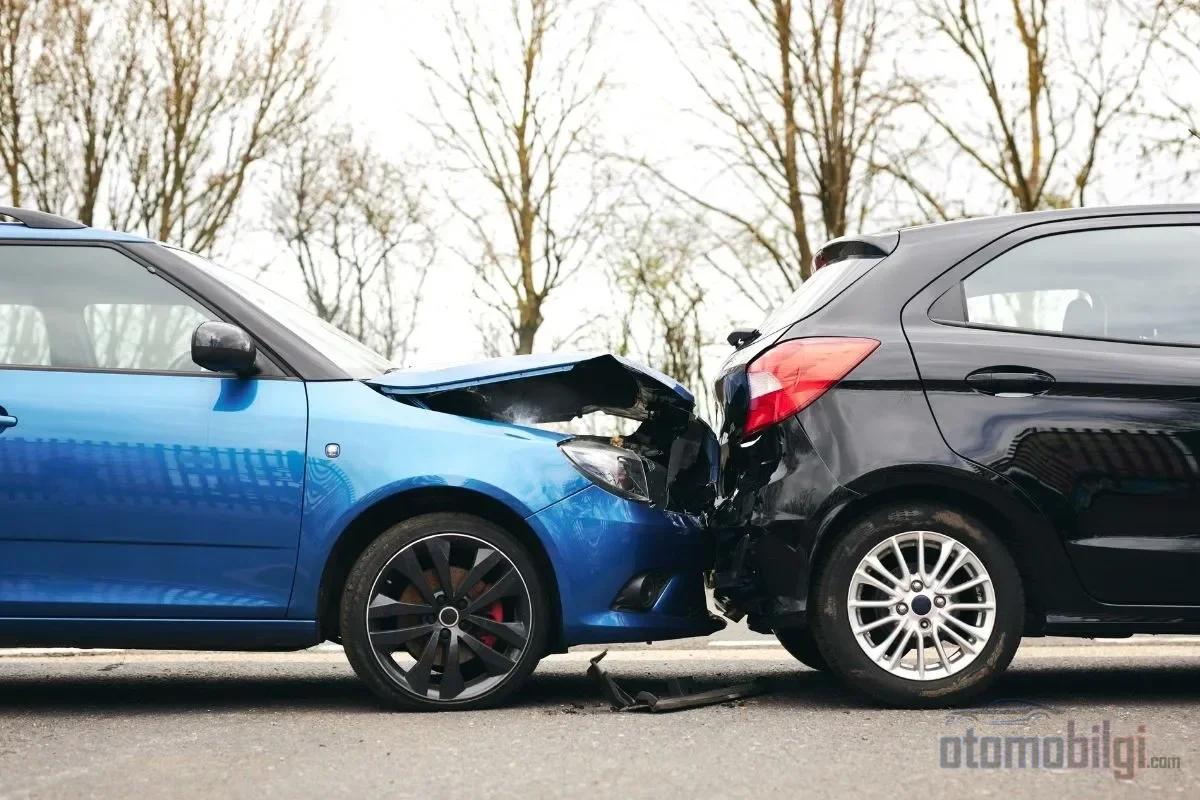
Although comprehensive insurance (kasko) is a type of insurance that secures your vehicle against theft, accidents, fire, and natural disasters, it does not cover every damage. The general terms on which the policy is based explicitly list the excluded situations and the risks covered only by additional agreements; the majority of damages rejected by the insurer stem from the reader overlooking these two distinctions. Below you will find in which cases kasko has no payment obligation, which coverages vary from policy to policy, and which steps those facing a denial decision can take.
Highlights
- Use above the legal alcohol limit is excluded from coverage in all kasko policies.
- In cases of driving without a license or in violation of the vehicle registration, the insurer does not pay.
- Flood, earthquake, hail, and key loss are covered only by additional agreements.
- Kasko is valid within the borders of Türkiye; an additional clause is required for abroad.
- Damage notification must generally be made in writing within 5 business days. must be made within the period stated.
Why Doesn't Kasko Cover Every Damage? Where Do the Policy Exclusions Come From?
The answer lies in a single sentence: all of kasko's coverages and exclusions are based on the document titled General Terms of Motor Vehicles Comprehensive Insurance issued by the Insurance Association, and this document meticulously defines not only what will be paid but also what will not be paid. If the insurer is to deny a claim, it looks for this justification either in the excluded situations section of the general terms or in the special terms written into your policy. In other words, a denial is not usually an arbitrary decision; it is the activation of the clauses you did not read on the day you signed.
This business has the same trap today as it did in the past: people look at their premium, glance at the coverage list, and skip the exclusions. Yet kasko's true character becomes clear on the exclusions page. The general terms divide the products into four: Narrow Kasko covers a portion of the basic risks, Kasko covers all of them, Extended Kasko covers a portion of additional risks on top of that, and Full Kasko covers all additional risks. The product name must be written in the policy in at least 16-point type; in other words, to learn at what level of protection you purchased, it is enough to look at the title of the document.
Excluded Situations: The Insurer's Definitive Grounds for Denial
Section A.5 of the general terms lists the situations that leave no room for debate. The main ones are as follows:
- War and similar events: Damages occurring during war, invasion, civil war, revolution, rebellion, and the military or administrative movements associated with them.
- Nuclear risks: Damages arising from nuclear fuel, radiation, and radioactive contamination.
- Use without a license: Damages occurring during use by a person who does not possess the driver's license required by legislation are excluded from coverage.
- Alcohol and drugs: The insurer does not pay for use under the influence of alcohol or drugs above the limit set in the traffic regulation.
- Intentionally caused damages: Damages caused by the intent of the insured, persons under their responsibility, or persons living with them, and vehicle abduction are not covered in this scope.
- Violation of intended use: Use of a vehicle insured for private purposes in a manner contrary to its registered purpose, such as unauthorized passenger transport.
The last item is not foreign, but recent: in 2026, a European court ruled that comprehensive coverage compensation was denied for the commercial use of a vehicle insured for private purposes. Declaring the vehicle's intended use accurately, reflecting its real-life situation, is not a cosmetic detail but a condition for the coverage to exist. A vehicle registered for private use effectively suspends its coverage on the day it is used for commercial work.
Does Comprehensive Insurance Pay for Drunk Driving? The Threshold and the Nuance
This is the most frequently asked question, and the answer has two layers. The first layer is clear-cut: accidents caused while under the influence of alcohol above the legal limit or under the influence of drugs are excluded from coverage in all comprehensive insurance policies. On the threshold, traffic regulations must be consulted; alcohol up to 0.50 promille poses no problem, while at 1.00 promille and above it is explicitly stated that comprehensive insurance will not come into play.
The second layer carries the nuance. According to the established view of the 17th Civil Chamber of the Court of Cassation, the driver being drunk does not by itself exclude the damage from coverage; alcohol must be the sole cause of the accident. The seatbelt example used to count among the classics of this profession: if the accident occurred for a reason independent of alcohol, the obligation to pay remains open to debate even if alcohol aggravated the consequences. In practice, insurance companies frequently cite alcohol as a reason for rejection; it should also be remembered that payment may still be made if fault is shared alongside alcohol, and that the insurer may claim back the payments it made from the at-fault driver.
Exemptions: Comprehensive Insurance Pays, But the Insured Assumes a Portion
An exception should not be confused with an exemption. An exception is a situation entirely excluded from coverage; an exemption means that the portion of the damage up to a certain amount or rate belongs to the insured. For example, in a policy with a 2% exemption, out of 10,000 TL of damage, 200 TL belongs to the insured and the rest to the insurer. The exemption must be clearly stated in the policy; otherwise it cannot be applied.
The most common practice on the market is the "Authorized Service Exemption" clause. This clause states that if you agree to go to a contracted private service in the event of damage, the exemption will not be applied. The snag here is that the difference in parts and labor between the authorized service and the contracted private service may be passed on to the insured. The premium saving looks appealing; the difference coming out of your pocket on the day of the damage is also part of the calculation. An exempt policy used to be a marginal choice, but now it has become far more widespread under premium pressure; it is enough to remember that along with the price, responsibility is also transferred to you.
Optional Coverages: Saying "I Have Full Comprehensive Insurance" Does Not Cover Everything
What raises the comprehensive insurance premium and establishes the real difference between products are the risks covered by additional agreements. These are listed in the general terms and may or may not be in your policy depending on your product level:
- Natural events: Earthquake, landslide, storm, hail, lightning, and flood with inundation are only covered with an additional agreement. To say "I have Kasko, flood will definitely be paid," this coverage must be written in your policy.
- Key loss: In some products, lock cylinder and key replacement is paid within certain limits in case the key is lost or stolen; in some policies, only roadside assistance is included and this service does not cover the cost of the key or coding. A police report may be requested when filing a claim.
- Damage from lack of oil, lack of water, freezing, and lack of maintenance: These cases can only be covered with an additional agreement.
- Mechanical and electronic failures: Kasko is not a repair or maintenance guarantee; it does not cover failures that do not result from a covered event, nor tire damage. Mechanical failure coverage is purchased with a separate premium.
- Personal belongings: Items such as glasses and bags are within basic coverage, while checks, cash, jewelry, mobile phones, and laptops are excluded.
Depreciation is a separate matter: as a rule, Kasko does not pay for market value loss. The faultless or slightly faulted party must direct this claim to the other vehicle's traffic insurance, within 15 days of the accident. If the vehicle is declared a total loss, payment is made from the market value minus the scrap value; that is, for a vehicle with a market value of 800,000 TL, the scrap value is deducted from the total. Finally, it should be remembered: Kasko is valid only within the borders of Türkiye. Accidents, theft, and damage occurring abroad are only covered with an additional agreement or a Green Card arrangement.
Misrepresentation: The Most Common Cause of Claim Denial
The largest portion of denial files is based on incorrect information given on the signing day. Hiding previous accidents, recording the wrong mileage, or misstating the intended use are the classics of this category. If intentional misrepresentation is detected, the accident damage is not paid; even if the error is not intentional, recalculation of the premium and, in the worst scenario, a reduction in the compensation come into play.
Equipment Not on the Registration and Valuation Issues
Steel rims, a multimedia system, or an LPG tank installed on the vehicle later are not counted within the insured value unless written on the registration. For these items to be covered, they must be written into the policy as an "Additional Accessories" item with their invoice value. Otherwise, on the day of damage, the cost of that part will not be covered, or disputes arise due to valuation issues, meaning the incorrect assessment of the vehicle's value. Insuring the vehicle with the correct valuation prevents both overpaying premiums and surprises based on market value in the event of a total loss.
Delay in Reporting Damage
According to the general terms, the damage must be reported in writing to the insurer within 5 business days of the accident or loss date. Late notification alone can be grounds for denial. If the insurer's investigation cannot be completed within three months, special provisions apply; but the most practical approach is to report the damage on the very day it occurs. Let me say this as a habit formed over thirty years: no file where the report, photos, and notification process was delayed ever turned out favorably afterward.
Clauses You Should Check Before Signing the Policy
| Checkpoint | What to Look For |
|---|---|
| Product type | Narrow, Extended or Fully Comprehensive; reading general and special conditions |
| Deductibles and clauses | Deductible rate, authorized/contracted service clause, parts-labor difference |
| Additional coverages | Presence of flood, earthquake, hail, abroad, key and replacement vehicle coverages |
| Parts condition | Original/equivalent parts requirement and market value assessment reference |
| No-claims bonus | Conditions for preserving the discount in accidents where the other party is fully at fault |
The no-claims item requires care: in accidents where the other party is fully at fault, or in a once-a-year glass damage claim, the no-claims bonus is generally preserved; with discounts of 40% or above, the discount is not entirely lost even if there is an accident. If a gap in coverage is left in the policy, a surcharge may apply. The common mistake is always the same: looking only at the price, not reading the policy, and signing the cheapest product instead of choosing coverage that suits your needs.
What to Do If a Claim Is Denied? The Objection Process
A denial decision is not the final word. The path to follow is quite clear:
- Submit a written objection to the insurance company against the denial letter.
- If you object to the expert report, the company is required to respond within 15 business days.
- If no result is achieved, apply to the Insurance Arbitration Commission or file a lawsuit; in comprehensive insurance disputes, arbitration is a fast and effective route.
It is known that the most common grounds for objection in denial files are alcohol, license and late notification. In these three areas, the strength of the evidence you hold determines the fate of your objection. The person who reads the exclusions before signing the policy is no longer a party to a dispute that will end up in court on the day of the loss; the entire experience of insurance fits inside this sentence.
Sources
- General Conditions of Motor Vehicle Own Damage (Kasko) Insurance – TSB
- Kasko Prices 2026 – Extended Kasko, Türkiye Insurance
- Kasko Insurance 2026 | Allianz Türkiye
- What Does Kasko Insurance Cover? 2026 – Your Insurer
- Court of Cassation 17th Civil Chamber Case No. 2018/4623 – Kazancı
- Does Kasko and Traffic Insurance Cover Damage in a Drunk Driving Accident? – Sigortam.net
- The Most Common Reasons in Kasko Damage Rejection Decisions – Ebru Ünsal
- Kasko Damage Rejection Objection and Lawsuit Process 2026 – Balgat Law
- Commercial Use of an Insured Vehicle – OGH 15.4.2026 – Munar