What Did the Turkish Automotive Industry Do When Imported Car Gates Opened?
Share This Page
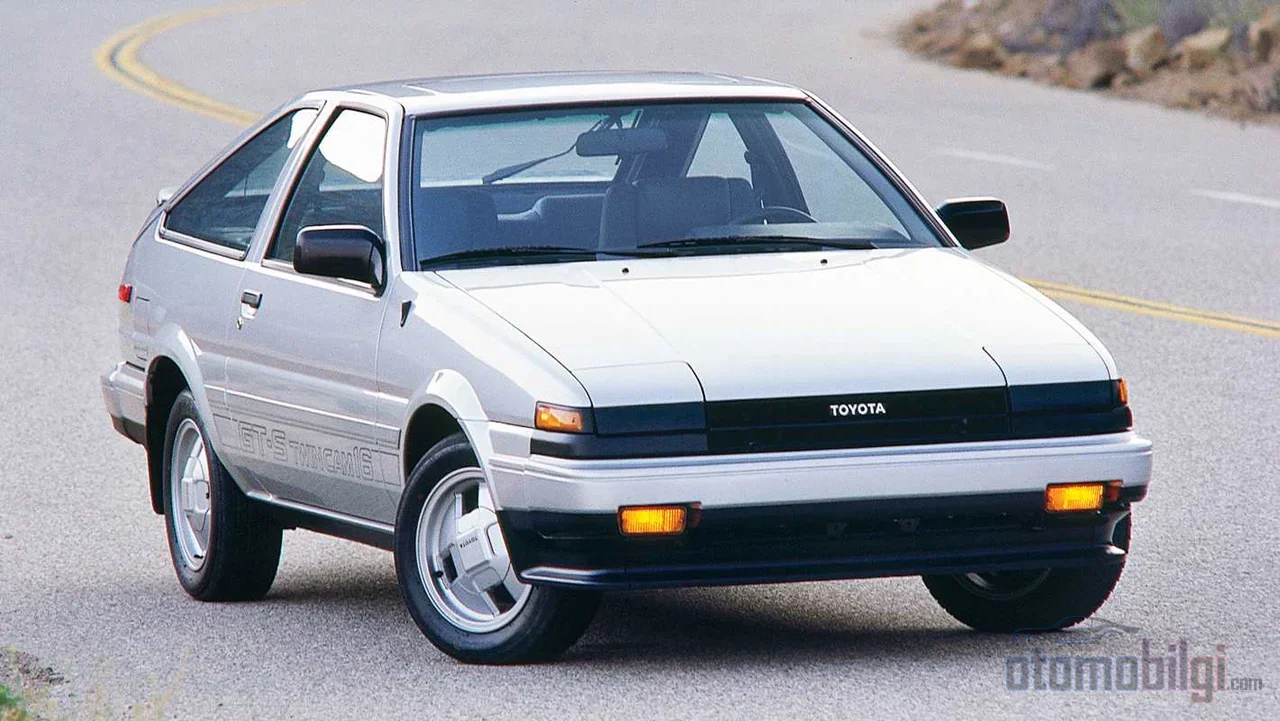
Until 1986, no automobiles were imported into Türkiye; when the doors opened that year, domestic manufacturers like Oyak Renault and Tofaş came face to face with competition but did not collapse - quite the opposite, they transformed by turning to exports and model diversification. This is the story of that transformation.
Highlights
- Automobile imports were banned until 1986; because the cost of an imported vehicle could reach about 4 times the vehicle's price.
- Turkish automotive production rose from 67,817 units in 1980 to 239,015 units in 1990.
- The market share of imported cars reached 23% in 1997.
- Tofaş's first export was made to Egypt with the Murat 124.
- Today, there are more than 250 global suppliers using Türkiye as a production base.
Imagine: after years of being able to choose only between two or three models, you woke up one morning and every car in the world was at your door. A true car gospel moment, right? So what did the factories do? Did they panic and shut down? No. And that is exactly what I will tell in this article: the opening of imports did not kill the Turkish automotive industry, it transformed it.
Everything Started with the January 24, 1980 Decisions
First, let's set the stage. Before 1980, the name of the game in Türkiye's economy was "import substitution": make it hard to buy foreign goods, make everything ourselves. It sounds like a nice idea, but on the automotive side, this meant "assembly line, not factory" for many years. From its founding, the country had grown accustomed to assembling cars rather than producing them; parts came from abroad, and we just screwed them together and hit the road.
The January 24, 1980 decisions reversed this picture. The currency was devalued by 32.7%, a daily exchange rate announcement system was adopted, and the state's share in the economy was reduced. Most importantly: the import substitution strategy was shelved, making way for an export-based growth model. The results spoke - total exports jumped from 2.9 billion dollars in 1980 to 5.9 billion dollars in 1983.
Now let's pause and ask: if it were you, managing a factory that had been protected for years in a closed economy, what would you do first when the doors opened? Lower the price, raise the quality, or rush into exports? Turkish manufacturers actually did all three - but first there was an obstacle.
Why and How Were the Doors to Imported Cars Opened in 1986?
Here is a detail most people don't know: even after the January 24 decisions, automobile imports did not begin immediately. No automobiles were imported into Türkiye until 1986. Why? For a very simple yet striking reason: due to customs duties and additional costs, the cost of importing a car reached about 4 times the vehicle's import price. In other words, a car that cost 100 units abroad would cost 400 units in Türkiye. In such a system, nobody was importing anyway; the door was technically open, but the math simply never added up.
With 1986, imported cars truly began to enter the Türkiye market. This was the first real stress test for domestic manufacturers. Buyers would now choose among different brands from around the world, not just a handful of models in the showroom. And guess what happened? Production did not collapse, it climbed: Turkish automotive production was 67,817 units in 1980 while it reached 239,015 units in 1990 - roughly a 3.5-fold increase. Competition woke up the industry.
Oyak, Tofaş and Others: Strategies for Surviving Competition
Diversifying models
Until the 80s, the industry had been producing for the domestic market, and it realized that with imports opening up, uniform production would not survive. The answer: expand the model range. Major manufacturers like Tofaş and Oyak Renault began offering vehicles in different segments; the era of holding the market with a single model was closing. Their roots were already deep - factories like Oyak-Renault, founded in 1968, and Tofaş, were products of the transition from assembly to full-scale manufacturing industry. Models like Anadol were also symbols of the era when automobile production was carried to industrial scale in Türkiye.
Turning to exports
The second strategy was applying the spirit of January 24 to the automobile: sell abroad. The turning point here was Tofaş; the first export was made to Egypt with the Murat 124, and this was a truly significant first for the Turkish automotive industry. Factories were now thinking not only about Türkiye's garages but also the roads of neighboring countries.
The impact of these two strategies multiplied in the 90s. Customs walls came down further, and trade and investment with the EU accelerated. The result is in this table:
| Period | What changed? |
|---|---|
| Before 1980 | Import substitution, mostly assembly industry |
| 1980-1986 | Export-oriented model, but no car imports |
| 1986 | Car imports began |
| 1980-1990 | Production rose from 67,817 to 239,015 units |
| 1997-1998 | Imported vehicles' market share was 23%, then 21% |
| 1999 | Domestic production fell 8%, imports rose 176% |
How Did the Domestic Parts Industry Survive the Removal of Customs Barriers?
Now let's come to the hero of the story but its lesser-known side: the parts (component) industry. Until the 90s, this sector had leaned on two things: Turkish capital and the power of technological licenses, plus the protection of customs walls. Let's think of it with an analogy from daily life: they were like a child riding a bicycle with training wheels. Safe, but a safety that in some way kept you off the real road.
When the customs walls came down, the training wheels were removed and the parts industry entered direct competition. Moreover, not only with rivals in Türkiye - there was also a revolution in the world automotive industry at the same time. The Japanese production system's "lean organization" approach began to be adopted by Western manufacturers toward the mid-90s; less waste, tighter quality, more rigorous supplier selection. In other words, the bar set for the Turkish parts manufacturer was rising not only locally but on a global scale.
The result? The sector was tested and came out strong. The rate of domestic parts usage in main industry was 15% in the 1960s and today, in some vehicles, it exceeds 90%. That is, nine out of every ten parts of a car can now be produced in Türkiye. In a field study of the supply industry conducted in the late 1990s, 91 firms responded - this alone shows how organized the sector is. And geography speaks too: like the main industry, the supply industry is concentrated mostly in Marmara, especially around the factories in Bursa.
Late 1990s: The Customs Union, Crises, and a Volatile Decade
The 1990s were not just a growth story; they were like a rollercoaster ride of ups and downs. The Customs Union process brought trade and investment with the EU into the fold and invigorated competition, but that same competition stung during crisis periods, and the end of the 1990s was a period of full volatility: In 1999, domestic production fell by 8% while imports rose by 176% - also under the influence of the Asia-originated global turbulence. The share of imported vehicles had reached 23% in 1997 and had declined to 21% in 1998. Domestic factories, under this pressure, had to increase their efficiency and export orientation a little more every year. In short, those who survived were those who did not sleep comfortably.
Did That Process Make Us a Global Production Base?
Here is that crossroads and today's picture. Without the push of the 80s and 90s, today's Turkish automotive industry would not exist. Today, Türkiye is a production center capable of designing and developing vehicles from scratch, manufacturing them, and carrying them all the way to the final stages of the value chain. More than 250 global suppliers use Türkiye as a production base. With 2025 data, we rank 12th in the world and 5th in Europe in motor vehicle production, and the highest automotive export in the history of the Republic was recorded. The sector exports to more than 190 countries and free zones ; even the supply industry's exports alone are at the level of 10 billion dollars . Daily at the two large factories in Bursa, 1,276 cars are produced, of which an average of 767 are exported. Reading this as a 15-year-old student truly gives me goosebumps, really.
But there is also the other side of the coin, and we need to tell it without exaggeration. The assessment within the sector that "being merely a production base is insufficient for a country with our potential and accumulation; our country must be able to take on the 'main industry' role" has long been voiced. In other words, should we make the world's cars but the names belong to others? This discussion gained a new layer with Togg: the framework of "a 61-year-old dream stretching from Devrim to Togg" tells exactly this. Meanwhile, there has recently been a change in Togg's partnership structure; the withdrawal of Vestel and Anadolu Group from the partnership was reported to the stock exchange. On the other hand, activity continues on the Tofaş front: The Competition Authority granted conditional approval with commitments to the Tofaş/Stellantis acquisition, and Tofaş raised its exports to an annual 39.4 thousand units with a 127% increase in the first half of 2026.
What Did We Actually Learn When the Doors Opened?
Let me sum it up, but not with memorized clichés. The opening of imports was not a story of extinction, but a story of trial. The January 24 decisions turned the country's economic compass toward exports; the import gate opened in 1986 pushed domestic producers toward diversifying models and entering foreign markets; the removal of customs walls weaned the parts industry off protective milk and carried it to a global scale. There were hard years like 1999, but production rising from 67,817 units in 1980 to 239,015 in 1990 showed the direction of the process. The seeds of our being Europe's 5th largest motor vehicle producer today were sown in those years. What do you think the next chapter of this story will be - a full-fledged "home-grown industry," or a deepening identity as a production base? I believe in the former so much that I even keep my notes accordingly.
Sources
- Automotive Industry Sector - ISI
- Main-Supplier Industry Relations in Advanced Automotive Industries - Atila Bedir, SPO 1999
- Türkiye's Leading and Rising Manufacturing Sector: Automotive - O. Yasar
- Automotive Supplier Parts Sector Report 2023 - TUBITAK
- Sectoral Analysis of the Automotive Industry in Türkiye - Y. Icingur
- Foreign Direct Investments in the Turkish Automotive Sector - D.O. Sevinecek, Uludag University
- January 24 decisions
- The January 24 Decisions Changed the Course of the Türkiye Story - Anadolu Agency
- Türkiye's Foreign Trade Policies in the 1980-2006 Period
- Corporate History - Tofas
- Competition in the Motor Vehicles Sector - Competition Authority
- Permission Granted for the Tofas/Stellantis Acquisition Transaction - Competition Authority
- Automotive Sector - Invest in Türkiye
- Türkiye Is Becoming a Global Production Base in the Automotive Sector - TRT Haber
- Türkiye Automotive Industry Report - Uludag Exporters' Associations
- What Should Türkiye Do in Automotive? - H. Suat Tuncel
- A 61-Year-Old Dream from Devrim to Togg - Anadolu Agency
- The Departure at Togg Officially Announced
- Bursa Has Become Türkiye's Locomotive in Automobile Production and Exports - Anadolu Agency
- Tofas Half-Year Results (1H26)
- Turkish automotive industry
- Macroeconomic Contributions of the Automotive Sector to the Turkish Economy - A.K. Basbug