Zero-Interest Period on the Nissan Townstar: Financing Opportunity for a Commercial Vehicle
Share This Page
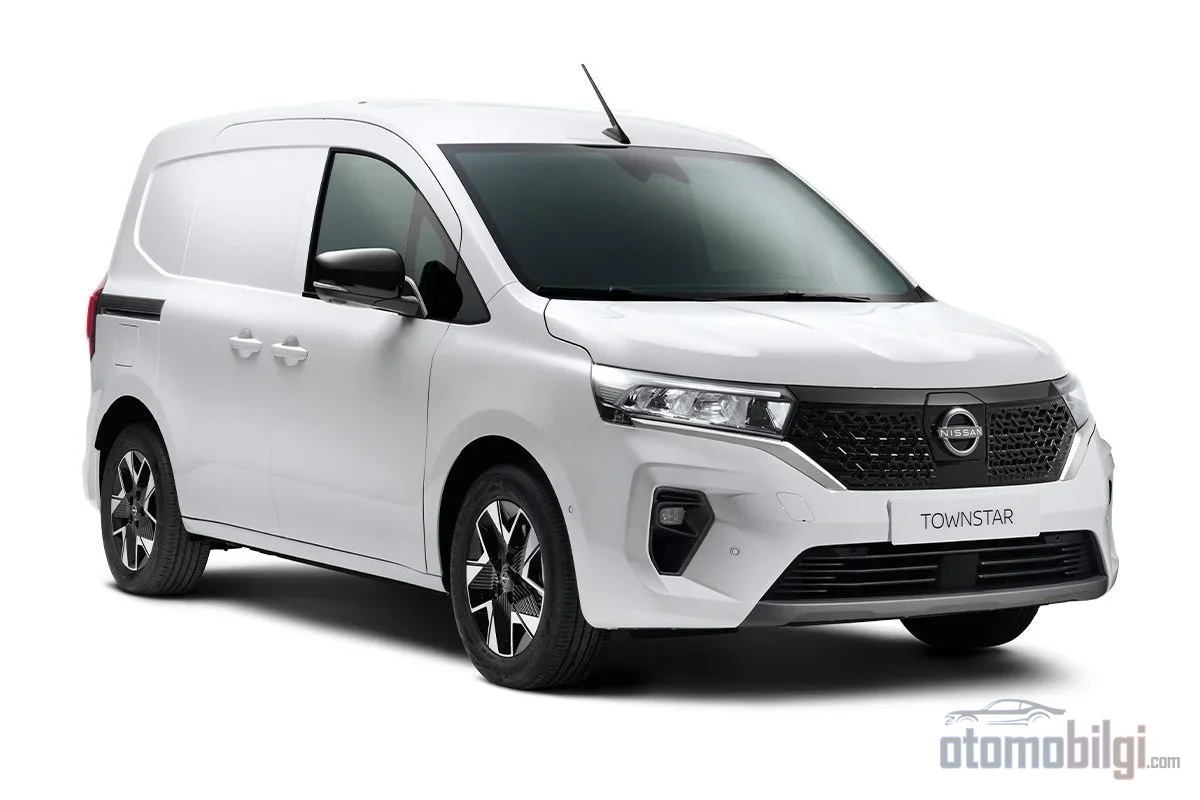
Starting in October, Nissan has launched an interest-free commercial loan campaign for SMEs on the Townstar family, offering up to TL 1,200,000 with 9-month deferred payment terms. The striking detail is that the scope is not limited to the gasoline van: the electric Townstar Van EV and Townstar Combi EV are also included in the same financing terms. The campaign is valid from October 1, 2026 and runs until Nissan's next announcement. The figure itself is a message in its own right: the ceiling amount, which was TL 800,000 in January, grew by 50% in nine months. For someone who has weathered this business, such a curve is not a blessing; it is a reflection of stock and market conditions in the mirror.
Highlights
- Townstar Van gasoline and electric, Combi EV: TL 1,200,000, 9 months, 0% interest (exclusive to SMEs)
- Townstar Van L2 long wheelbase TL 50,000 cash discount or a combination of cash discount and loan
- Campaign October 1, 2026 valid as of; vehicles limited to stock
- In the January-September period, while the passenger car market 15.45% contracted, light commercial vehicles declined by only around 5% declined
- Interest-free 6-month loans for commercial customers are also in effect on the Qashqai and Juke
Terms of the Townstar Campaign: Who Gets What, on Which Version?
The backbone of the campaign is the commercial credit package defined exclusively for SMEs. The same figure applies to the L1 short wheelbase gasoline Townstar Van and the electric Van: TL 1,200,000, 9 months, 0% interest. The Combi EV is also covered under the same scope. In other words, interest-free financing embraces all three of the three versions; this is the clearest sign that the manufacturer did not want to leave the electric side out of the campaign.
The picture is a bit different on the L2 long wheelbase. Here, a TL 50,000 cash purchase discount takes center stage; if you wish, you can combine this cash discount with the 9-month 0% interest loan of TL 1,200,000. It should also be noted that, pursuant to the BDDK's decision No. 10099 dated 21.02.2022, the interest-free loan is applied within limits referenced to the final invoice value. Campaign vehicles are limited to stock, cannot be combined with other campaigns, and the distributor reserves the right to change the terms. Those who have been reading these announcements for years know: this reserved right is a standard sentence in an environment where campaigns are in fact renegotiated every month.
How Much Is the Campaign Price?
There is a visible difference between the list prices and the campaign figures. For the gasoline Townstar Van's 1.3 DIG-T 130PS 6MT L1 Visia version, the list price is TL 1,429,000; in the campaign table, this figure drops to TL 1,151,000. On the Combi EV, the starting price appears with two figures ranging between TL 2,437,900 and TL 2,486,500 in secondary transfers; the full detail of the official price list is not consistent in the copies I found online, so it would be wise to confirm the exact figure with an authorized dealer. Let us also add that the two-tone (black roof) option is TL 25,000 offered for sale at a premium.
| Version | Financing / Discount | Condition |
|---|---|---|
| Townstar Van Gasoline L1 | TL 1,200,000, 9 months, 0% interest | SME, commercial loan |
| Townstar Van EV | TL 1,200,000, 9 months, 0% interest | SME, commercial loan |
| Townstar Combi EV | 1,200,000 TL, 9 months, 0% interest | SME, commercial loan |
| Townstar Van Gasoline L2 | 50,000 TL cash discount | SME; can be combined with the loan |
Evolution Throughout the Year: From 800,000 TL to 1,200,000 TL
Tracking the campaign's course throughout the year is the most instructive exercise for explaining why Nissan has opened up such a wide package now. In January, SMEs were offered on the Townstar Van 800,000 TL at 0% interest for 12 months plus a cash discount. In May, the same setup was extended to the Combi EV, again at 800,000 TL and 12 months. In August, the term was still 12 months, and this was the point where the Townstar stood apart, while most passenger models had a 6-month term.
In October, the balance shifted: the amount rose to 1,200,000 TL and the term dropped to 9 months. With a simple calculation, a 50% increase in the amount was offset by a quarter reduction in the term. While interest-free loans used to mean long-term packages that softened the monthly payment, the function has now reversed: high-amount, short-term packages are growing to cover a large portion of the vehicle's invoice value. As prices climb, fixed loan ceilings become ineffective; it is no surprise that the distributor updates it every month. Let us also note that in the interim, a version with a 1,000,000 TL amount titled "pay in 3 months" was also announced - meaning the package changed hands not once but several times within the year.
Market Environment: Why Is the Weight on Commercial Customers?
To understand the campaign's target profile, it is enough to look at the overall picture of the year. In the January-September period, total car and light commercial vehicle sales shrunk by 13.39% to 803,465 units; the decline on the car side was 15.45%. The light commercial market, with a contraction of about 5%, remained noticeably more resilient than passenger cars; there were even periods in the early months of the year when this segment was still growing. Considering that the market shrank by 25% in harsh months like July, the relative stability on the commercial side is like a calm lake compared to the consumer market.
This asymmetry explains why Nissan directed its 0% interest loans almost entirely to commercial and SME customers. Courting the segment where sales are most resilient with financing advantages is the classic way to preserve volume in a shrinking market. The same logic operates on the passenger side too, but with softer tools: while cash discounts mostly cover individual buyers as well, interest-free loans are given against a commercial invoice.
Parallel Moves on the Qashqai and Juke
The same announcement set also includes passenger models. For commercial customers, the Qashqai Mild Hybrid in N-Design, Platinum and Platinum Premium trims is offered a 1,000,000 TL loan at 0% interest for 6 months ; the Designpack version is listed at a limited-number promotional turnkey price of 2,269,000 TL . On the e-POWER versions, things go a step further: there is a 100,000 TL cash discount open to individual and commercial customers on the Designpack, Skypack, N-Design and Platinum, while on the Platinum Premium this discount is 400,000 TL goes up to, and alongside it again a 1,000,000 TL loan at 0% interest for 6 months is added.
On the Juke the figures are more modest but the structure is the same: on the Platinum, the commercial customer gets 360,000 TL at 0% interest for 6 months; on the Platinum Premium this is accompanied by a 100,000 TL cash discount. In the X-Trail's MY25 model year, via the authorized dealer page a 1,500,000 TL commercial loan at 0% interest for 6 months is valid. In March, the Juke offered individual buyers a 100 thousand TL cash discount and 240 thousand TL at 0% interest for 12 months; seven months later the term has dropped to 6, and the loan amount has been readjusted on the passenger car side as well. The pattern is the same for every model: shortening term, growing amount.
The Paradox in Electric Light Commercial Vehicles: The Campaign's Real Target
Here is the most interesting knot in the matter. While the electric car market is growing rapidly - 15,074 electric cars were sold in September, with market share jumping from 14.39% to 23.65% in one year - the electric light commercial side is barely moving. In the first five months of the year, the best-selling electric light commercial model was the Ford Custom with 223 units; the Opel Combo followed it with 108 units. These volumes describe the dimensions of a niche rather than a market. The same data also shows that the Townstar failed to stand out on this list.
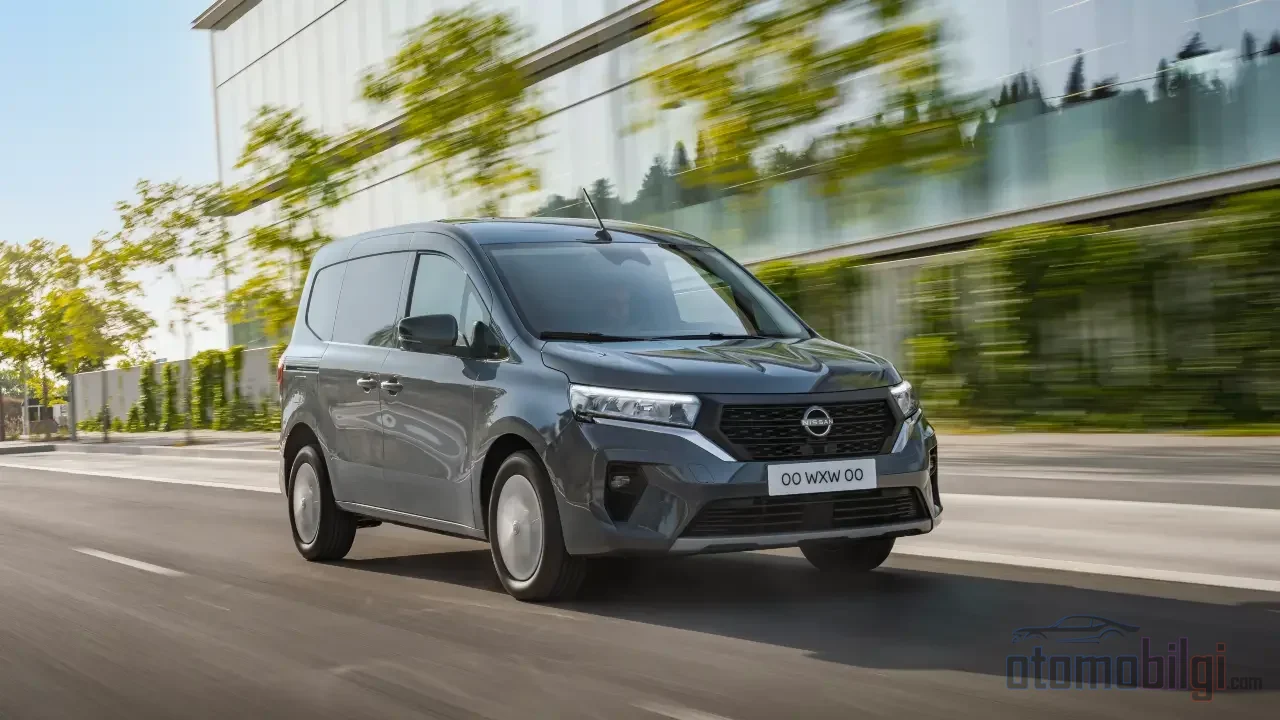
In this light, placing the electric Townstar models at the very heart of the 0% interest loan is a meaningful move. The Combi EV is advertised with 395 km of range in city driving and 281 km of range in mixed driving; in technical briefings, the 45 kWh battery and 245 Nm of torque stand out. In other words, the product sits in a framework that makes sense for fleets doing last-mile delivery and city service work. The problem is not the product but demand: the small business owner's transition to electric commercial vehicles is a matter of operating habits alongside price and charging infrastructure. The interest-free loan is the most direct tool designed to soften the price leg of this transition. Including the electric versions in the campaign is itself the demand-generation effort; it is no coincidence.
What Does It Mean from the Buyer's Perspective?
To list the practical outcomes: if you are an SME-registered business and you are considering a Townstar with an invoice value below 1.2 million TL, that means you have an amount you can finance for 9 months without paying interest. When read together with the campaign price - for example, roughly a 278 thousand TL difference between the list price and the campaign on the L1 Visia - the overall picture looks attractive on paper. However, three warnings need to be kept on the table. First, the campaign is limited to stock and conditions may change in the next announcement; in this market, waiting in reliance on the campaign calendar is often the same as waiting for the stock to run out. Second, the loan limit is calculated based on the final invoice value, meaning that as you add options and equipment, the portion covered by the ceiling decreases. Third, the indecision over the electric versions in the campaign price list continues; there is no reason at all to sign before obtaining an official quote prior to purchase.
A note for those not thinking long-term: the 9-month installment package is a structure designed not to lighten the monthly installment burden, but to zero out interest in the total cost. A business wanting to extend its installments can find a more comfortable cash flow at the bank with different arrangements. The 0% interest here is a purchase trigger, not a cash flow management tool.
Conclusion: The Strategy Behind the Numbers
Read on its own, this campaign looks like an ordinary month's financing announcement. But when you put together the credit ceiling that grew throughout the year, the shrinking car market, the relatively resilient light commercial segment, and the nearly motionless electric commercial demand, the picture becomes clear: Nissan is consolidating its position with interest-free financing in the segment where it can best protect its volume, while aiming the same weapon at its weakest link, the electric light commercial. The fact that 800,000 TL was enough in January but 1,200,000 TL is required in October shows this strategy is racing against price inflation. It is unknown what figure the next announcement will bring; but the likelihood of this ceiling moving upward for the rest of the year is the most reasonable forecast that can be read from the campaign's own internal dynamics.
Sources
- 2026 Model Year Current New Vehicle Campaigns - Nissan Türkiye
- Recommended Turnkey Price List (October 2026) - Nissan Türkiye
- New Nissan Townstar Van - Nissan Türkiye
- Nissan New Vehicle Campaigns - Authorized Dealer
- ODMD Market Assessment Reports
- Nissan Townstar Van January 2026 New Vehicle Campaign
- Nissan Townstar Combi EV May 2026 New Vehicle Campaign
- Nissan August 2026 Campaign
- Nissan Townstar Current Campaign Price List
- Nissan October 2026 New Vehicle Prices
- Nissan Price List October 2026
- Light commercial vehicle market is "going electric" - Anadolu Agency
- 2026 automotive sales: The market shrank, electric vehicles rose
- Nissan Townstar Combi EV Prices