Toyota Offers Vehicles with 36-Month Fixed Installments and No Down Payment
Share This Page
Toyota, in cooperation with Yapı Kredi Leasing in Türkiye, is offering Toyota Leasing through its program, which allows the full cost of the vehicle to be financed with no down payment. The model works with fixed installments over 12, 24, and 36 months, covers the entire passenger and light commercial lineup, and aims to protect the cash flow of businesses holding a tax plate. In this article, we examine the program's conditions, sample installments, and how it differs from current loan campaigns.
Highlights
- Up to 100% financing, no down payment; terms of 12, 24, or 36 months with fixed installments
- Passenger and light commercial all Toyota models included
- Corolla over 36 months, excluding VAT ₺76.153–₺101.925 monthly installment
- Sample payment amounts Valid between October 1-31, 2026
- In the loan channel, financing closes on vehicles over 2 million TL; leasing fills this gap
What is Toyota Leasing and on what terms does it operate?
Toyota Leasing is a financial leasing model offered within the framework of the partnership Toyota Türkiye established with Yapı Kredi Finansal Kiralama. As of October 15, 2026, the program, announced with a table published on its official page, allows the entire cost of the vehicle to be financed; in other words, there is no classic leasing option or the down payment typically required with dealer loans. Installments are set at a fixed amount, and the term options are 12, 24, and 36 months .
The program's scope is kept broad: Toyota's entire passenger and light commercial vehicle lineup can be purchased through leasing. The announcement also highlights the point that leasing does not affect your loan limit at the bank . For anyone who has been following this market for more than three decades, it is not hard to appreciate the weight of this sentence; in the past, leasing was largely the domain of commercial fleet customers, but now brands are trying to extend this channel to individual buyers.
Who can benefit?
The program is open to individuals and legal entities holding a tax plate . In other words, both a sole proprietor tradesperson and the owner of a limited company can apply under the same conditions. The up-to-100% loan campaign on light commercial models also covers individual customers; therefore, the scope needs to be checked separately by vehicle and channel.
Who retains ownership in a lease?
In financial leasing, ownership of the vehicle remains with the leasing company for the duration of the contract. The practical consequence of this is that collateral requirements are kept low and the business's equity is not tied up in vehicle investment. For a commercial customer who wants to keep cash in the business rather than in the vehicle, this is precisely the main appeal: the cost of the vehicle can be financed without coming out of working capital.
How much are the 36-month installments, using the Corolla as an example?
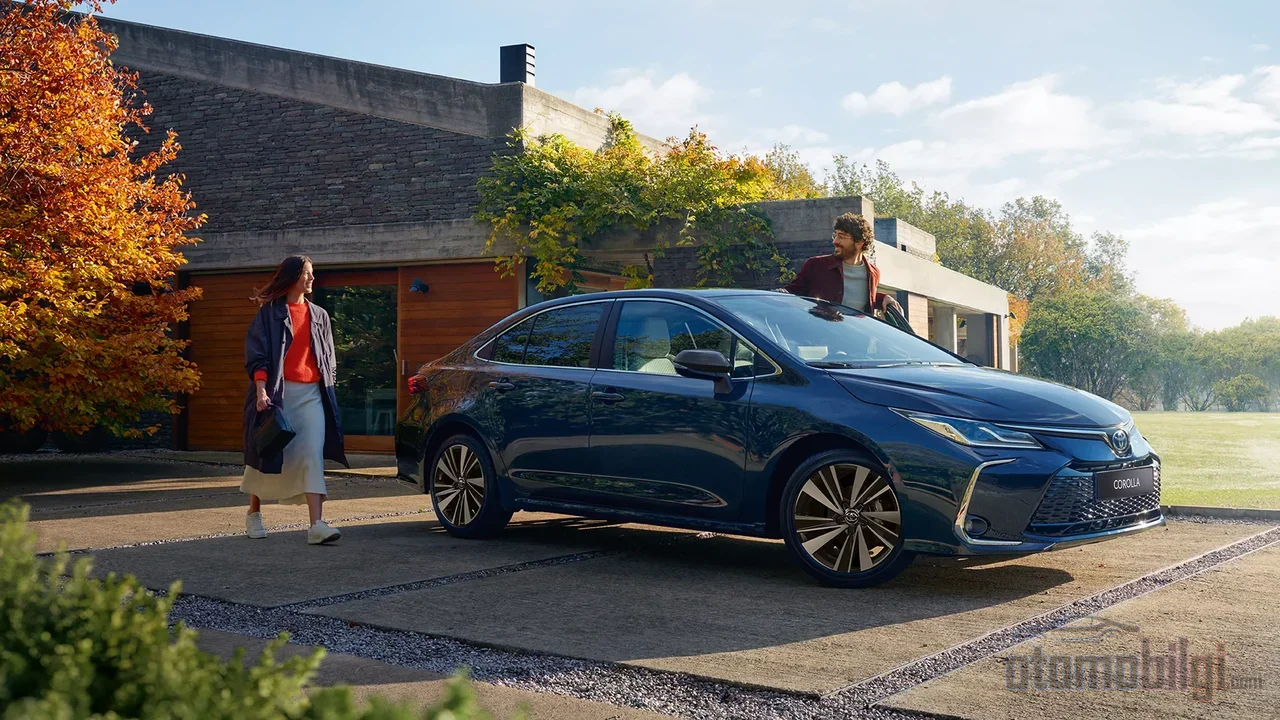
The payment table published on Toyota's official leasing page provides concrete figures based on the Corolla Sedan lineup. With amounts excluding VAT and based on vehicles in opaque colors, for the 1.5 Vision Plus Multidrive S version ₺164.396 over 12 months, ₺98.132 over 24 months, and over 36 months ₺76.153 a monthly installment is projected; the total repayment over a 36-month term comes to ₺2,741,499.
| Version (Corolla 1.5) | 36-Month Installment (excluding VAT) | 36-Month Total |
|---|---|---|
| Vision Plus Multidrive S | ₺76,153 | ₺2,741,499 |
| Dream Multidrive S | ₺83,322 | ₺2,999,605 |
| Dream X-Pack | ₺88,167 | ₺3,174,001 |
| Flame X-Pack | ₺90,492 | ₺3,257,711 |
| Passion X-Pack | ₺101,925 | ₺3,669,284 |
There are two points worth noting in the table. First, the figures apply to vehicles in solid colors; choosing a metallic or pearl color raises the amount. Second, the installments are stated excluding VAT, so taxes must also be added when calculating the total cost of ownership. The example payment amounts are October 1–31, 2026 stated to be valid between these dates; it should also be noted in this context that the brand reserves the right to change the campaign terms at any time.
What is the difference between no-down-payment leasing and a 0% interest loan?
Toyota is also running aggressive campaigns through the loan channel in the same period, and the buyer faces two separate doors. While 0% interest loans look appealing, they are limited: Proace City with the Dream and Passion X-Pack, and Proace Cargo for a 0% interest option on ₺1,000,000 with a 6-month term is offered; the Cargo campaign is open only to corporate customers. In short, 0% interest is squeezed into short terms and specific amount limits.
Toyota Leasing, on the other hand, answers a different need: terms extending up to 36 months, 100% financing, and the entire model range. For a business that wants to keep its budget predictable with a fixed installment over three years, leasing is a more realistic solution than a six-month 0% loan. On the other hand, vehicle loan campaigns with up to 100% financing are also open to corporate and sole proprietorship businesses across all models; in other words, businesses can evaluate both channels. The choice will be shaped by term needs and total cost sensitivity.
Does the above-price limit in the loan channel fill leasing's gap?
The table in Toyota's loan calculator contains clear restrictions based on vehicle price for vehicle loans: for vehicles up to ₺400,000, a 70% ratio with a 48-month term can be applied; in the ₺800,001–1,200,000 band, the ratio drops to 30% and the term to 24 months; in the ₺1,200,001–2,000,000 range, 20% remains with a 12-month term. Vehicle loans cannot be used for vehicles priced at ₺2,000,001 and above and the minimum down payment is set at ₺10,000. The allocation fee is five per thousand of the loan amount, plus BSMV.
In the context of October 2026 prices, the meaning of this restriction becomes clear: the Corolla Sedan's campaign price is ₺1,965,000, list price 2,545,500 TL; the Proace City starts from 1,711,000 TL. The campaign Corolla sits just below the top band in the loan channel, but if a payment close to the list price is involved, the door narrows; for models above the list, the channel closes completely. Leasing, which comes with a 100% financing promise, offers buyers an alternative exactly in this price zone. The thinning of banks' loan channels in the market's high price segment is already the main dynamo pushing brands into such partnerships.
The cost of the long term: how much does the total cost rise?
The comfort of a low installment is not free. In the official payment table, the Vision Plus version's total repayment over a 12-month term is 1,972,755 TL, while over a 36-month term this amount 2,741,499 TL rises to; the difference is approximately 770 thousand TL. As the term lengthens, the monthly burden eases but the total money paid increases noticeably. This is a fact stemming from the nature of financing; the campaign being advantageous and being the most economically correct choice are not the same thing.
The question of leasing versus bank loan is also part of this calculation. In commercial vehicle and equipment investments, cash flow protection and tax advantages put leasing ahead, while in passenger car purchases it is debated that credit can be more favorable in some cases in terms of expense deduction. Toyota Leasing combining passenger and light commercial vehicles in the same program requires the decision to be calculated separately for every business. Thirty years ago such a program coming onto the agenda would not even have been possible; today's course of interest rates and vehicle prices has placed alternative financing channels at the center.
Evaluation from a business perspective
For a commercial business, Toyota Leasing's main contribution is on the balance sheet side. When the vehicle investment is financed without eroding equity, capital stays within the core business; the fixed-installment structure makes budget planning easier in an environment shaped by inflation and exchange rate fluctuations. Ownership remaining with the leasing company also reduces the need for collateral. The partnership established with an established player in the sector also inspires confidence in the program's continuity; the party's 2025 activity report states with a volume of 59 billion TL it maintained its sector leadership.
In return, how the vehicle's relationship with the business will conclude at the end of the contract, the mileage and usage conditions, and the terms of the end-of-term purchase option are headings that must definitely be clarified before applying. For these details not included in the announcement, it would be appropriate to request the current contract terms from the dealer. What must be remembered is this: the sample payments cover only October, and the brand reserves the right to change the conditions.
Conclusion: Fixed installment, 0% loan, or classic loan?
Toyota Leasing, with its no-down-payment and 100% financing structure, offers a real alternative especially for vehicles exceeding the 2 million TL band, where the loan channel has narrowed. For large short-term purchases, 0% interest loans still retain their appeal; if long term, fixed installments, and a structure covering the entire lineup are preferred, leasing is the model that should come to the table. The decision will come down to the buyer's term needs, cash flow plan, and tax position combined. But one fact remains: the softening of the down-payment requirement in vehicle financing is no longer the exception, it has become the rule.
Sources
- Toyota Leasing - Vehicle Purchase via Leasing for Companies
- Promotional Products Detail | Toyota - Yapı Kredi Leasing
- Loans of Up to 100 - Toyota
- Loans of Up to 100% on Toyota Light Commercial Models
- Vehicle Loan Calculation 2026 - Toyota
- New Car Campaigns October 2026 - Toyota
- Corolla - October 2026 Campaign - Toyota
- Commercial Vehicle Campaigns October 2026 - Toyota Professional
- Leasing | Affiliates - Yapı Kredi
- Yapı Kredi Finansal Kiralama A.O. Activity Report 31/12/2025
- Leasing or Bank Loan: Comparative Cost Analysis